Solid-State Batteries' Real Bottleneck Is Lithium Sulfide, Not the Cell
One material, lithium sulfide, sets more than half of a solid-state cell's cost. Four Korean-listed companies work on it, and none has a confirmed supply contract yet.
Seoul — China has named 'initial large-scale commercialization' of solid-state batteries (cells that use a solid rather than liquid electrolyte) a national goal for 2030, according to MTN. When the technology scales, the first thing to run short is not the cell but lithium sulfide (Li2S). Gotion says it will lift Li2S capacity from 300 tonnes in 2026 to 50,000 tonnes in 2030 (Gasgoo), about 167 times. Today's price is $12,000/kg, 240 times the $50/kg needed for the economics to work (Korea Electrotechnology Research Institute figure, reported by Daum).
At a glance
| Company | Bottleneck part | Nature of the boost | Evidence | What to check next |
|---|---|---|---|---|
| Isu Specialty Chemical (457190) | Commercial Li2S output (150t/yr) | Expectation | Press reports only | A formal supply contract with a cell maker; utilization rate |
| Lake Materials (281740) | Li2S plant (120t/yr) | Expectation | Press reports only | Move from samples to mass-production orders; expansion funding |
| Lotte Energy Materials (020150) | Sulfide solid electrolyte (70t pilot) and copper foil for solid-state cells | Expectation | None | Electrolyte mass-production timeline; copper foil's weight in sales |
| EcoPro BM (247540) | Solid electrolyte and lithium-metal anode material | Expectation | Press reports only | Whether the Samsung SDI tie-up turns into deliveries |
This piece draws on Paper Trail's own theme research (as of 2026-10-11 11:26 KST), source articles, and company price and filing data. Price moves run from the July 10, 2026 close to the October 8 close. None of the four has a contract confirmed through a filing.
Bottleneck 1: Why lithium sulfide runs short
Per Gotion, solid electrolyte is 70–80% of cell cost, and Li2S is 70–80% of electrolyte cost (Gasgoo). Paper Trail's research reads that as Li2S alone setting more than half of the cell's cost.
Few can make it. The process needs high heat and high energy, is sensitive to moisture, and has low yield (the share of input that becomes usable product). In our research record, the producers able to make it at scale are Isu Specialty Chemical (150t), Lake Materials (120t), Lotte Energy Materials (70t pilot), Gotion (300t in 2026) and Idemitsu of Japan. Expansion needs process validation and engineering partners, and takes a year or two at least.
Demand grows far faster than cell output. Gotion plans to take Li2S from 300t in 2026 to 50,000t in 2030 (about 167x) and finished solid electrolyte from 2,000t to 100,000t (50x). Each added cell pulls in much more than one cell's worth of material.
Bottleneck 2: Why lithium-metal foil runs short
Next-generation cells use a lithium-metal anode with about 10 times the energy density of graphite, according to EcoPro. The trouble is thickness. Foil a few microns thick (a micron is a thousandth of a millimeter) is hard to make with conventional extrusion and rolling, Benchmark Minerals says.
Benchmark puts global lithium-metal capacity at 7,500 tonnes a year in 2023, with less than half of it battery grade. China holds more than 90%. For 2026 alone, Benchmark sees demand above 10 GWh against available supply of roughly 5–10 GWh. In the U.S., Albemarle is the only domestic producer.
Isu Specialty Chemical: production has started, contracts have not
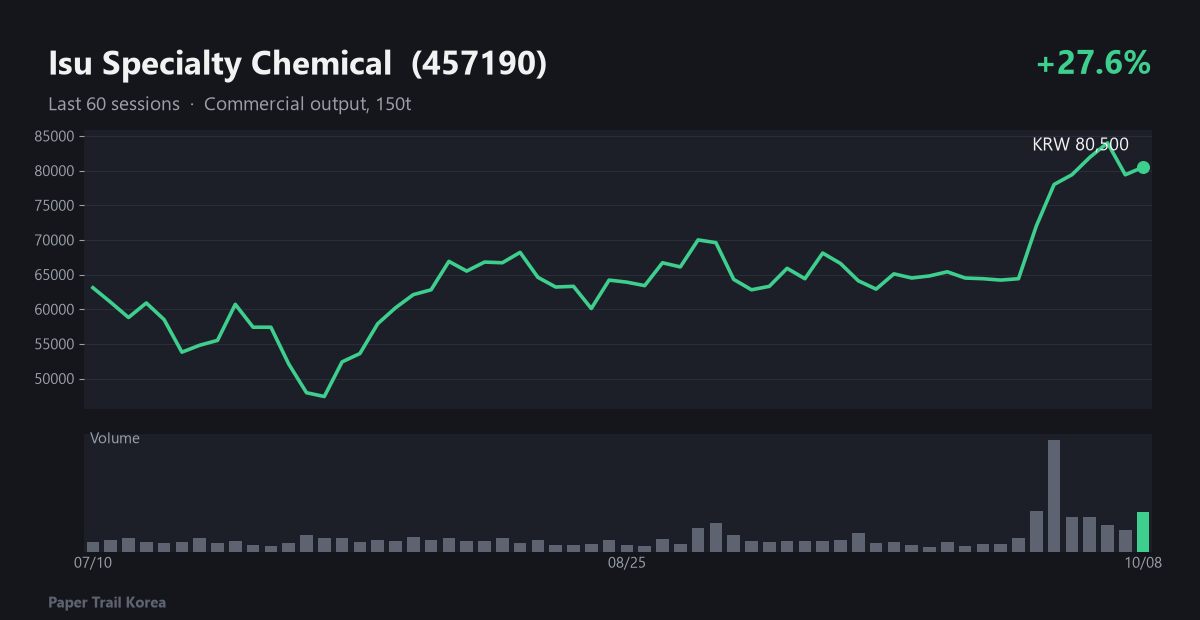
It makes lithium sulfide. Paper Trail's research treats it as Korea's only independent listed company built mainly around Li2S. The plant is designed for 150t a year and could expand to 500t if the market grows (fnnews). Ridenews reported that commercial production began in October. The company has been testing Li2S with Korean, U.S. and Japanese battery makers since 2021, and Meritz Securities expects full-scale supply from 2027 (Asia Economy). No formal supply contract or market share has been confirmed. Gross margin in our research record is 16.3%, up 11.9 percentage points from a year earlier. The stock is up 27.6% over the period and 4.2% below its period-high close of 84,000 won. Filings in the past week are an investor-relations meeting notice and a futures price-limit notice. None concerns orders or production.
Two things to check. One is whether yield and utilization at the commercial plant are disclosed and the 500t expansion is made official. The other is whether Samsung SDI, LG Energy Solution or SK On sign a formal supply deal. The premise weakens if Chinese rivals expand at low prices, if customers announce in-house production, or if the gross-margin improvement reverses.
Lake Materials: the plant exists, sales are still samples
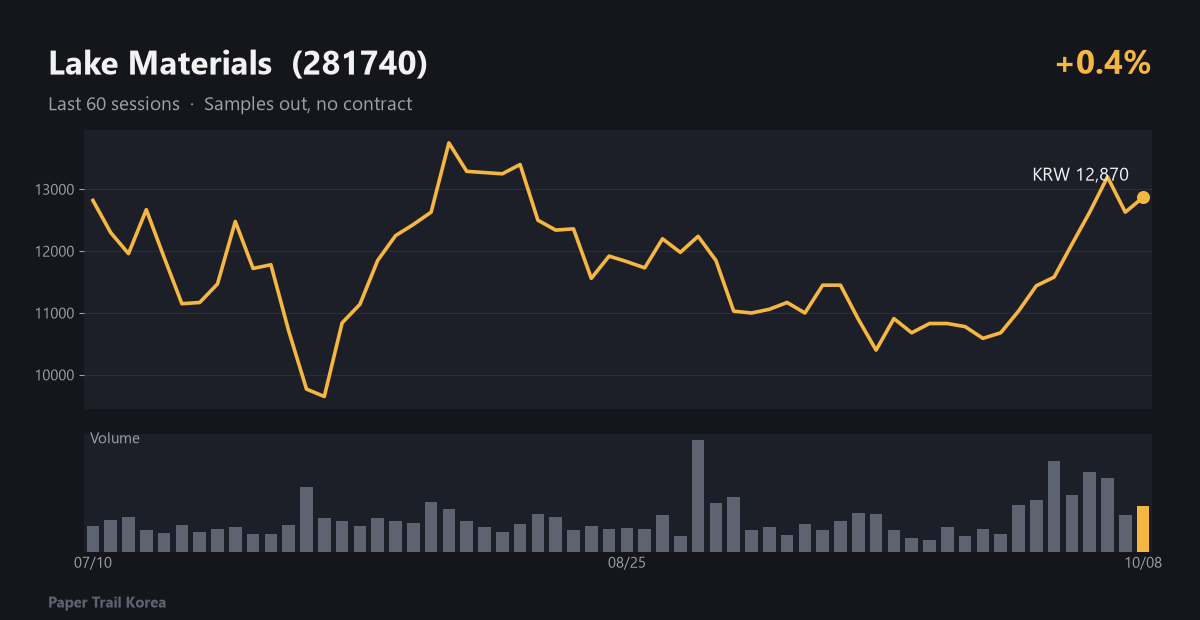
Its subsidiary Lake Technology finished a 120t-a-year Li2S plant at the end of 2023. Our research record shows samples going to Samsung SDI, LG Energy Solution, EcoPro BM and Lotte Energy Materials. The company has set a target of 20% of sales from solid-state by 2028 (Korea Economic Daily), which means the share is smaller today. The 9.2% net margin and 19.1% sales growth in our record do not come only from this theme. The stock is up 0.4% over the period and 6.4% below its period high. There were no filings in the past week and no news in the past three days.
Watch for a shift from samples to a mass-production contract, and for capital spending on expansion. Debt ratio in our record is 151% and free cash flow (cash from operations minus investment) is negative. A share issue to fund expansion would dilute holders. A failed sample test, or rivals locking in prices, would also matter.
Lotte Energy Materials: the solid-state piece is still a pilot
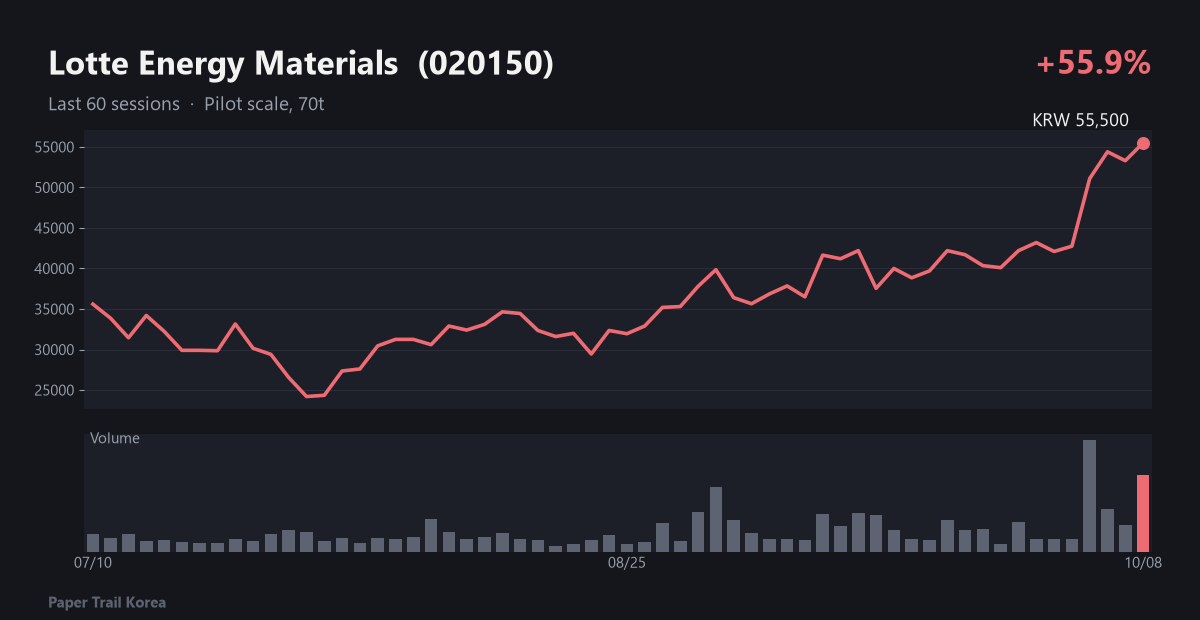
In our research record, the links to this theme are a sulfide solid electrolyte (70t pilot, meaning trial-scale production) and copper foil for solid-state cells. No order or filing for the electrolyte side has been confirmed. Recent coverage is mostly about circuit foil supply and copper foil utilization and yield. Business Post named yield improvement as the challenge. So it is hard to separate how much of the stock's move is about solid-state. The stock is up 55.9% over the period, and the October 8 close is the period high. No filings tied to this theme appeared in the past week.
Watch whether the electrolyte pilot leads to a production timeline or a customer contract. Also track copper foil utilization and yield. That helps tell whether the rise is about solid-state or about AI and energy-storage (ESS) demand for foil.
EcoPro BM: lithium metal sits with an affiliate
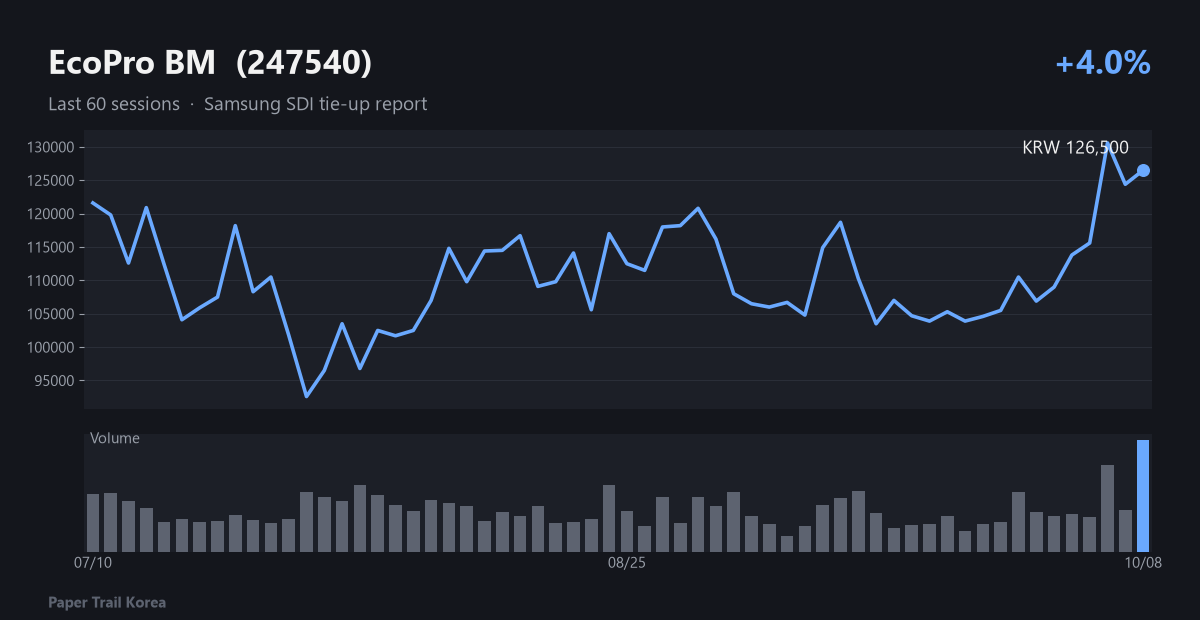
Our research record lists solid electrolyte and lithium-metal anode material as its links to the theme. Two ties are confirmed. There is a report of cooperation with Samsung SDI (MTN). Affiliate EcoPro Innovation is co-developing lithium-metal anode material with Hydro-Québec, building the full process from lithium metal to ultrathin foil in Canada by March 2027 (kbmaeil). That is an affiliate's project, so whether it reaches EcoPro BM's sales needs separate confirmation. The theme's share of sales is not in our data. The stock is up 4.0% over the period and 3.1% below its period high. Filings in the past week are an investor-relations meeting, a fair-disclosure notice, and a futures and options price-limit notice. Their titles show no link to this theme. Rights to new shares were listed on September 21.
Check whether the Samsung SDI cooperation moves past samples into delivery contracts. Lithium metal is a market where China holds over 90%, and ultrathin foil is hard to make, so a firm production schedule matters. Reports also describe a broad rally in battery materials and ESS names (Maeil Business, Chosun Ilbo), so the move cannot be pinned on this theme alone.
What to be careful about
- The timing is far off. Samsung SDI plans prototype production in 2027, and LG Energy Solution and SK On in 2027–2029. LG Energy Solution's anode-free solid-state cell is a 2030 target (MTN). Heavy material demand comes after that.
- Pricing power may not sit in Korea. Gotion says it plans 300t in 2026 alone, twice Isu Specialty Chemical's 150t. Low-priced Chinese expansion or customers making Li2S in-house could keep prices from holding.
- Theme revenue is small or mixed. Lake Materials targets 20% of sales from solid-state only by 2028. Lotte Energy Materials and EcoPro BM have large other businesses. None of the four has a contract confirmed through a filing.
- The rise has several causes. A recovery in battery stocks and expectations for ESS demand overlapped in the same weeks. Abroad, Solid Power (SLDP) is a sulfide electrolyte rival with an SK On supply contract. Our research notes its small market cap and the need to check survival and dilution risk.