Solid-State Battery Stocks: The Real Bottleneck Is Lithium Sulfide
Lithium sulfide is likely to run short before the battery cells do. We checked what four listed companies have confirmed and what they have not.
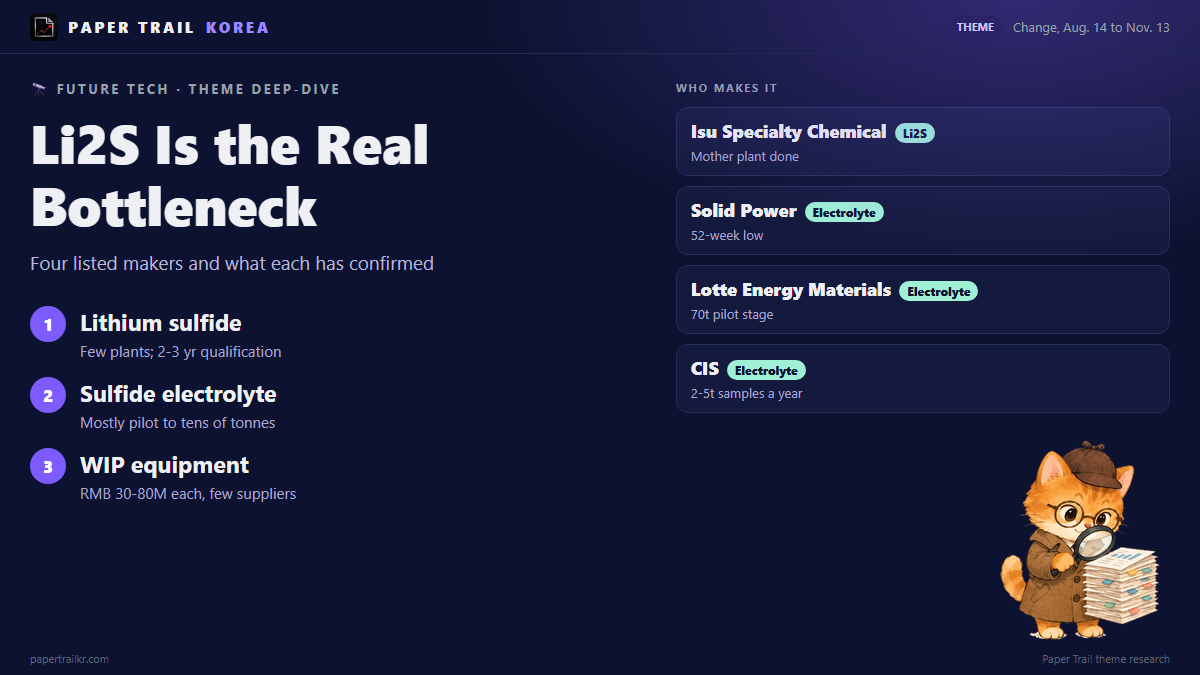
Seoul — Paper Trail's own theme research (researched 2026-11-15 11:22 KST) finds that solid-state batteries move from pilot to early mass production in 2027-2029, then spread to EVs, robots and energy storage (ESS) in the 2030s. SMM estimates that hot isostatic pressing (WIP, equipment that presses material from all sides) alone will be a market of more than RMB 6 billion by 2030. The part most likely to run short first is lithium sulfide (Li2S), not the cell. China's Gotion says Li2S makes up 50-64% of a cell's cost (Gasgoo).
At a glance
| Stock | Bottleneck part | Nature of the news | Evidence | What to check next |
|---|---|---|---|---|
| Isu Specialty Chemical | High-purity Li2S | Expectation | Press reports only | New battery-maker supply deals; yield and margin data from the mother plant |
| Solid Power | Sulfide electrolyte (and Li2S) | Expectation | Press reports only | Whether the Korean JV's 500t breaks ground; new financing |
| Lotte Energy Materials | Sulfide solid electrolyte | Expectation | Press reports only | Whether the 1,200t expansion happens and who adopts it |
| CIS | Solid electrolyte material and dedicated equipment | Expectation | Press reports only | Whether the North American NDA becomes a supply contract |
None of the four has a confirmed large order for this material in our data.
Bottleneck 1: High-purity lithium sulfide has very few producers
Only a handful of plants worldwide make battery-grade Li2S at commercial scale. Our research lists Isu Specialty Chemical at 150t growing to 500t, Idemitsu at 1,000t a year targeted for 2027 (about $143 million, battery-news.de), Solid Power at 30t growing to 75t, and Gotion planning 1,000t in 2026. A new line takes more than a year to build. Cell and carmaker qualification adds another 2-3 years, according to reports on CATL and others, so capacity keeps trailing demand.
Each cell also needs more of it. A solid electrolyte acts as both separator and electrolyte, so it is used in larger weight than a liquid one. Gotion says Li2S is 70-80% of electrolyte cost.
Bottleneck 2: Sulfide solid electrolyte is still at pilot scale
Solid electrolyte is the finished material made from Li2S. Lotte Energy Materials runs a 70t pilot and plans 1,200t (Digital Daily), CIS makes a few tonnes of samples a year, and Solivis aims for 42t then 400t (SMM). Most are at pilot to tens-of-tonnes scale. Once a supplier is qualified, switching is hard, which is why early position matters.
There is a price pressure too. Gotion says the current price (about RMB 1.3 million per tonne) has to fall sharply before solid-state cells can sell widely.
Bottleneck 3: Dedicated equipment costs tens of millions of yuan a unit
SMM says equipment is 12-14% of total investment in a 1GWh line, and WIP machines alone are about 13% of equipment value. Each costs RMB 30-80 million, a pilot line needs 2-4, and few makers supply them, so lead times are long. SMM judges large-scale mass production before 2030 to be very difficult.
Isu Specialty Chemical: the plant is built, the contracts are not yet
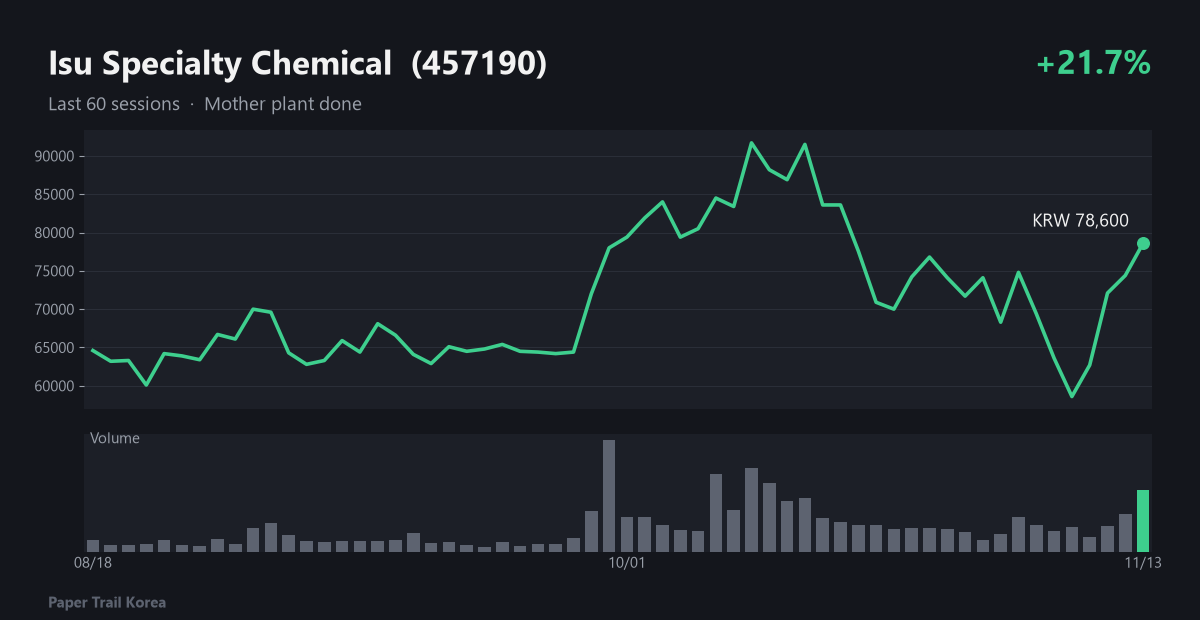
Isu makes lithium sulfide. Paper Trail research says it has Korea's only commercial mother plant (the base synthesis facility), starting at 150t with room to reach 500t. Lead Economy also reported the completion and called profitability the next test. The company has supplied prototypes to EcoPro BM, but our data shows no large supply contract. Gross margin is 16.3%, up 11.9 points from a year earlier and 3.6 points from the prior quarter, though we cannot tell how much of that comes from this material. The stock is up 21.7% since August 18 and 14.3% below its period high of 91,700 won. None of the filings in the past week relate to this theme; they were stock-futures price-limit notices.
The two things to watch are an official update on mother-plant yield and profitability, and additional supply contracts with battery makers. Cheap bulk supply from Idemitsu or Gotion, a failed qualification, or customers making their own Li2S would weaken the case.
Solid Power: it has customers, but the numbers are weak
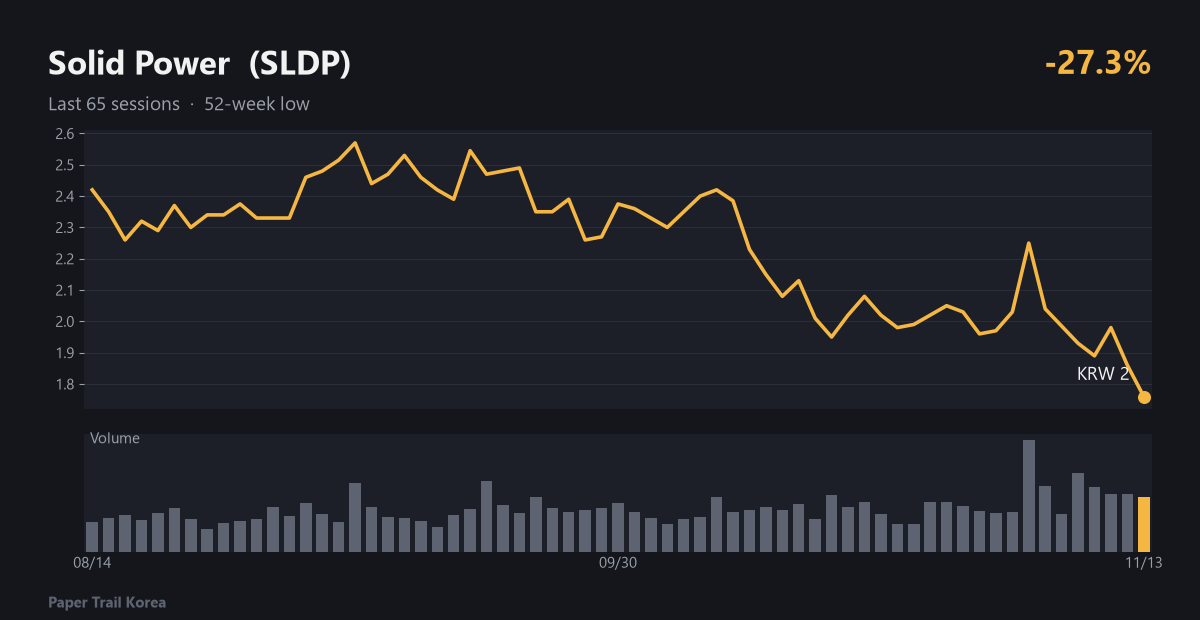
The U.S.-listed company makes sulfide electrolyte and Li2S. Paper Trail research says it holds supply and validation agreements with SK On, Samsung SDI and BMW, and is pursuing up to 500t through a Korean JV. SK On moved its mass-production target up to 2029 (Korea Herald). But revenue fell 93.5% year over year and gross margin dropped to -941.2%. The stock is down 27.3% since August 14, sits at a 52-week low of $1.76, and is 31.5% below its period high. It filed an earnings 8-K on November 3 and a 10-Q on November 4, and TipRanks summarized the call as covering progress, risks and liquidity.
Watch whether agreements convert to mass-production contracts and whether the 500t JV is funded and started. New equity financing or a customer cutting its contract would be the clearest warning signs.
Lotte Energy Materials: large company, unknown share for this material
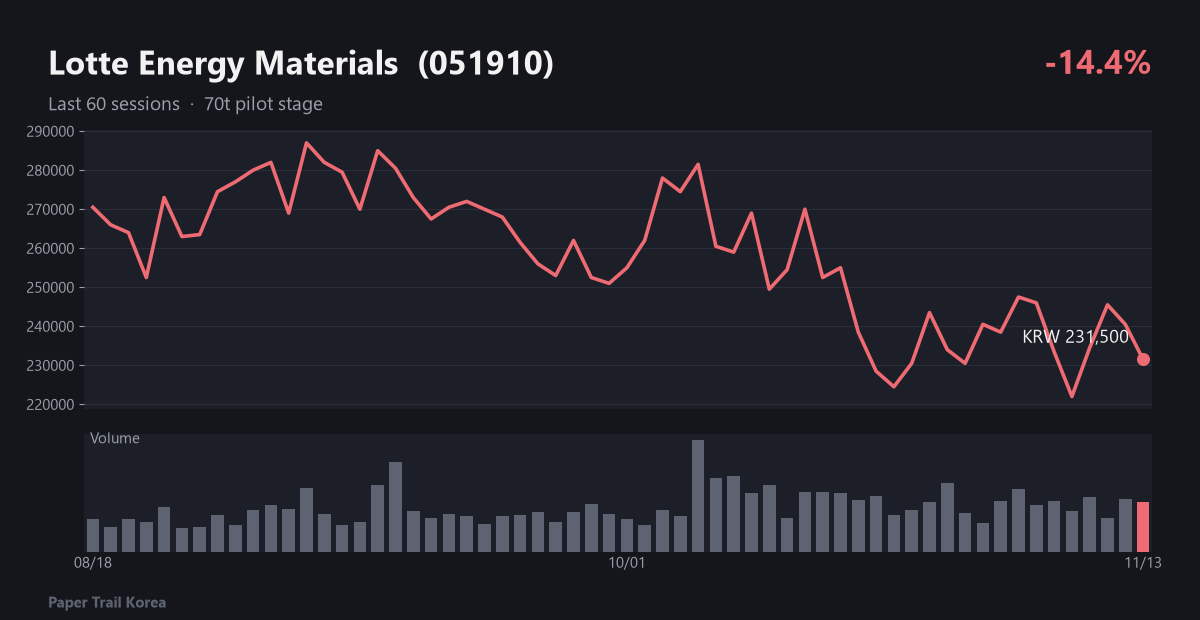
The company is preparing sulfide solid electrolyte. A 2024 report said it spent 15 billion won on a 70t pilot at its Iksan plant and planned 1,200t in 2026 and mass production in 2027. Our research puts its market cap at about $13.59 billion, the largest of the four, so this material is likely a small or mixed part of total sales. Our data has no breakdown. The stock is down 14.4% since August 18 and 19.3% below its period high. No filings in the past week relate to this theme.
Check whether the 1,200t expansion actually went ahead and whether a customer has adopted the material. The plan is two years old, so an official schedule update is the most useful new information.
CIS: clean finances, sample-scale output
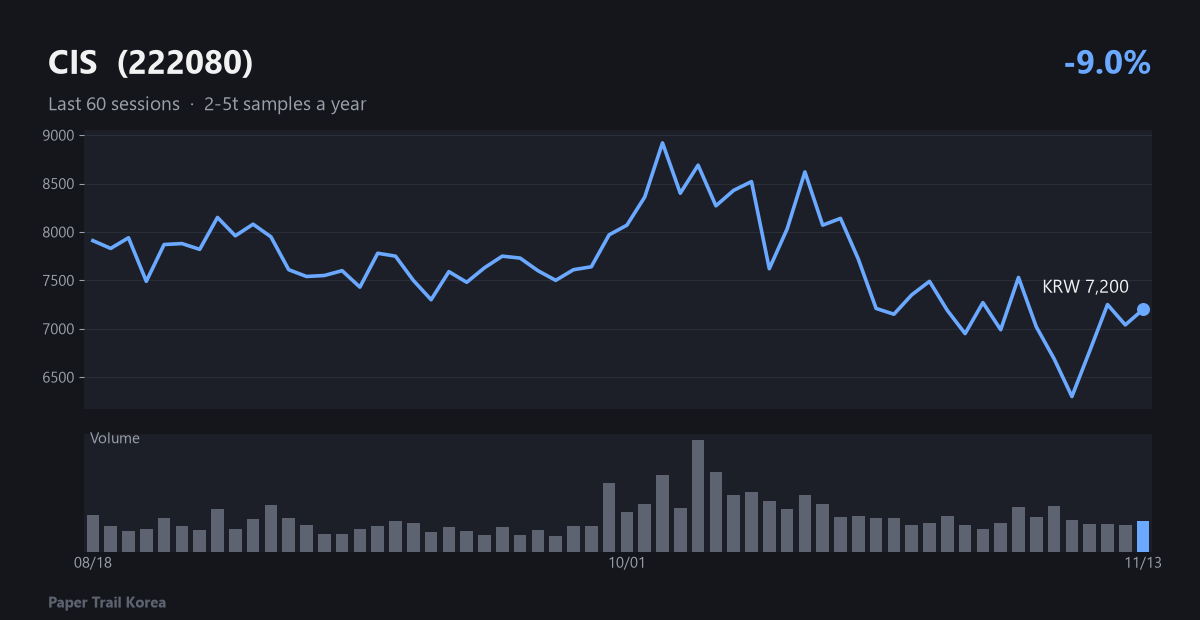
CIS makes solid electrolyte material and the equipment to produce it. It makes a few tonnes of samples a year at its Daegu plant, and it reportedly signed an NDA with a North American energy company. An NDA is a step before a deal, not a supply contract. Our research notes gross margin up 24.4 points year over year, positive free cash flow and no borrowings. The stock is down 9.0% since August 18 and 19.3% below its period high. No filings in the past week relate to this theme.
The key question is whether the NDA turns into a supply contract with volumes, and whether a plan to scale beyond a few tonnes appears.
What to be careful about in this theme
- A bottleneck is not the same as profit. None of the four has a confirmed large order for this material, and Solid Power's revenue fell 93.5%.
- Foreign rivals can crush prices. Idemitsu and Gotion each plan 1,000t, large next to Isu's 500t expansion.
- Customers can make it themselves. If battery makers bring Li2S production in-house, outside suppliers lose volume.
- The timeline is long. Qualification takes 2-3 years and SMM doubts large-scale production before 2030, so recent price moves are far from the 2030s earnings.
- The price figures here are period changes and distance from the period high. They are not a basis for trading decisions.